After reading this, you will have a framework for translating your definition of a “settled” life to a potential partner’s family, and a clearer lens to see when their financial questions are about genuine concern versus a bid for control.
The first time it happens, it feels like a simple misunderstanding. You’re in a formal meeting, maybe the third one, describing your work. You talk about a project you’re proud of, the skills you’re building. They smile politely, and then the uncle or the father asks, “But what is the monthly take-home? Is it a permanent role?”
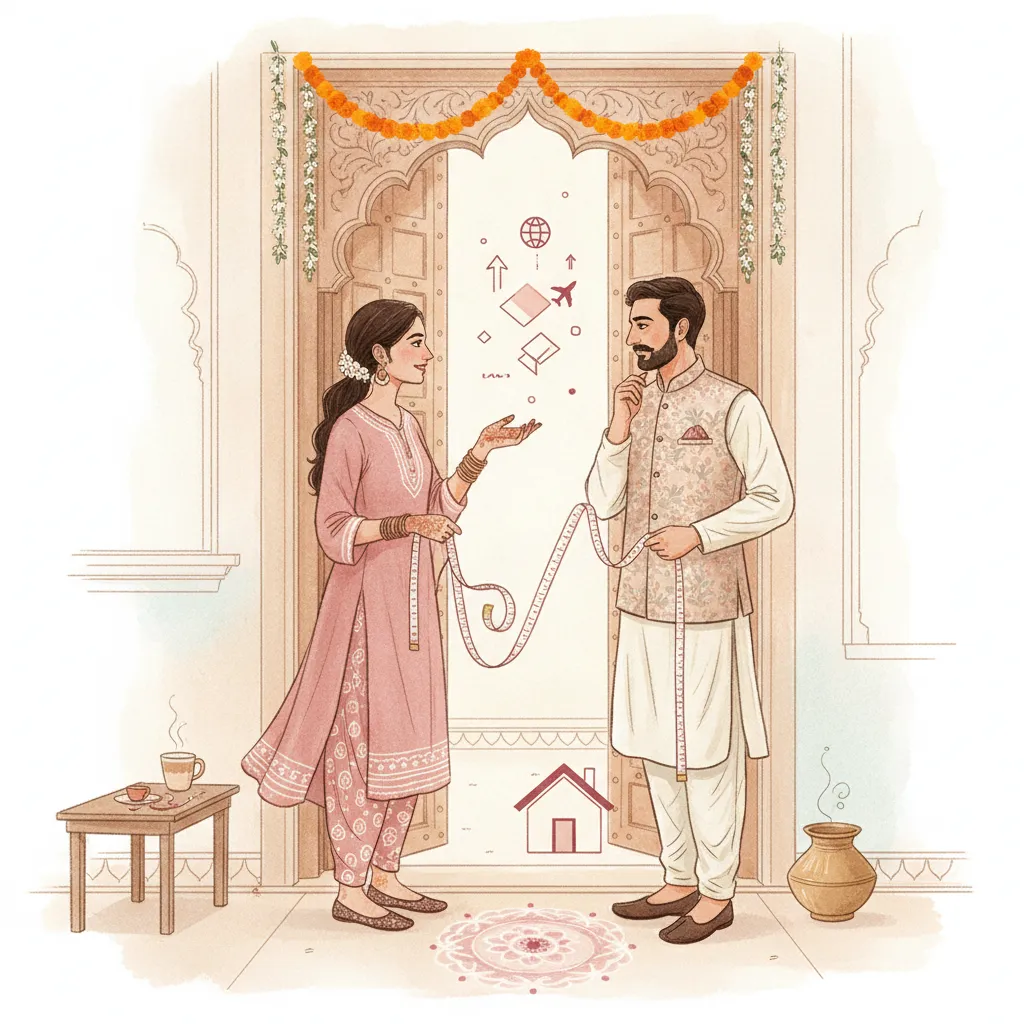
You are talking about your life’s trajectory. They are asking for a fixed point on a map. And in that gap, entire potential marriages are lost. This isn’t a simple communication problem. It’s a collision of two completely different blueprints for what makes a life secure. For your parents’ generation, stability was a house deed, a provident fund, a job you retired from after thirty years. It was a fortress built against the precariousness they had seen or experienced. Their questions come from a place of care; parents search for safety; you search for a partner, and their definition of safety was forged in a different economy.
For you, stability might be a different shape entirely. It might be the “runway” of savings that lets you switch projects. It might be a portfolio of freelance clients, where risk is spread out, not concentrated in one employer. It might be the human capital of your skills, which let you work from Coimbatore or Chandigarh or even another country. You see your life as a vessel built for navigating seas; they are looking for a house with deep foundations. Neither view is wrong. But believing they are speaking the same language is the first, and most expensive, mistake.
When the Numbers Replace the Person
The friction begins when their questions stop being about understanding your life and start being about reducing you to a data point. The translation fails, and the conversation becomes an audit.
Consider Ajay, a 27-year-old in Patna on his third attempt at the civil services exam. He is studious, deeply committed, and lives frugally on family support and income from tutoring. He meets Priya, a 26-year-old freelance graphic designer from Bhopal whose income, while variable, is substantial and growing. In their second meeting, with families present, Priya’s father asks Ajay, "So if this attempt also doesn't work out, what is the backup? How much are you earning from tuition right now?"
The question is practical on the surface. But its effect is to frame Ajay’s ambition as a liability. It puts him in a position of defending a path that, by its very nature, involves uncertainty. The focus shifts from his character, discipline, and long-term goal to his current, and deliberately temporary, lack of a salary. The probe is subtle: how does he react to being financially questioned? Does he get defensive? Does he make promises he can't keep? His response teaches them how much pressure he is willing to absorb.
The innocent motive here is a father’s genuine anxiety about his daughter’s future. He wants to see a plan. The extractive motive is to establish a dynamic where Ajay is perpetually in a deficit, someone whose career choices require their approval and oversight.
Now, reverse the situation. Kavita is a 28-year-old nurse at a private hospital in Nagpur. Her work is demanding, her shifts are brutal, but her job is secure. She meets a potential match whose family runs a successful logistics business. They meet at the family’s lavish home, surrounded by signs of their status. This display of wealth is a tactic; it reframes the entire conversation. It establishes their dominance and implicitly asks, "Can you contribute to this?" In this context, his father repeatedly circles back to her salary. "Is there a scope for promotion? Can you do private nursing for more money? My son is planning to expand the business, we will need a strong second income." He never asks about her patients, the stress of her work, or why she chose a caring profession. He is not interviewing a daughter-in-law; he is assessing a financial asset. This scene is written with a woman being questioned and a man’s family judging, but swap the roles and the pressure feels identical. It is a dynamic about control, not a script for a gender.
The pattern is the same: the person’s work, skills, and contribution are ignored in favour of a single metric—the monthly salary. This isn't a conversation about building a future together. It is an appraisal.
The Vocabulary of a Different Stability
You cannot win an argument when you are using two different dictionaries. The task is not to defend your choices but to translate them into a language of stability they can understand. Arguing that "my way is better" is a losing strategy. Translating "this is also a form of safety" is how you build a bridge.
Instead of just stating your profession, frame it using the vocabulary of security.
- If you are a freelancer or business owner: Talk about your
runway. "I keep six months of expenses in a liquid fund. That’s my personal safety net, so that a slow quarter doesn't become a crisis." This demonstrates foresight and planning, the very traits they value. - If you have multiple income streams: Talk about your
portfolio. "My primary income is from my marketing job, but I also do some corporate training on weekends. I don't like having all my security tied to one employer." This reframes what they might see as "not having a proper job" into a sophisticated risk-management strategy. - If your value is in your skills: Talk about your
human capital. "The technology I work with changes every two years. My real stability isn't my current company, it's that my skills are in high demand. I can get a job in any major city within a month." This translates the concept of a job from a location to an ability.
The goal is not to lecture them on the new economy. It is to show them that you share their core value—a secure future—but are building it with different tools.
Here is a question you can ask, word for word, when you feel the conversation turning into an interrogation:
"It sounds like long-term security is really important to your family, and it is to me too. Can I share how I think about building that security in my field?"
A constructive answer sounds like this: “Okay, I don't really get this freelance stuff. How do you plan for big expenses then?” This models genuine, imperfect curiosity. It signals openness and a willingness to update their own model of the world. They are inviting you to translate.
A dismissive answer sounds like this: "That is all fine, but in the end, a person needs a steady, fixed salary every month. How much is that?" This tells you they are not listening. They are not seeking to understand; they are waiting for you to provide the number that fits their pre-existing spreadsheet. This is a major signal. The conversation has stalled.
Finding the Line Between Prudence and Intrusion
Prudence has a purpose; intrusion has a goal. The task is to tell them apart. A family that doesn't ask about finances at all might be disinterested or naive. The difference is between due diligence and a hostile takeover of your life's balance sheet. The real warning signs are not in the questions themselves, but in their timing, their insistence, and how the answers are used.
Intrusion often follows an escalating pattern. It begins not with a direct demand, but by framing your life choices as a problem for them. Your plan to get a PhD becomes "How will we manage if you leave your job?" Your ambition to start a business is met with "That is a nice dream, but you have to be practical for the family." Your life plan is being presented as an inconvenience to their existing system.
From there, it can escalate to a premature demand for proof. They ask for payslips, bank statements, or your ITR password before there's even a mutual 'yes' to proceed. This isn't the innocent, if awkward, conversation two people might have six months later when they're seriously planning to apply for a home loan, an event which would require sharing proof of income. This is an early-stage demand for access, not to build trust, but to gain leverage.
If you are transparent about a financial reality—like a ₹8 lakh student loan or the fact you send money home to your parents—watch how that information is treated. Does it become a point of understanding, or is it weaponised? The punishment for transparency is when your vulnerability is used against you in a later conversation. Your loan becomes the reason you can’t switch jobs; your family obligations become a mark against your own financial stability. It’s no longer your history; it’s a liability they can use to extract a concession.
The final stage is the unilateral co-opting of your finances. They start making plans for your money before you are even a unit. "With your salary, we can finally renovate the upstairs room," or "You should give your ATM card to your future husband; he will manage it better." This is a clear signal that they view your income not as yours, or even as part of a future couple's joint fund, but as a new revenue stream for the existing family unit. This is a critical moment to understand the difference between healthy joint finances and lost independence.
After a difficult conversation, run this external test: Can you name one new thing you learned about their values, and one new thing they learned about yours? If the exchange was purely data extraction, the answer for one or both will be no.
The Question That Isn't About Money
Ultimately, this generational conversation is not about rupees. It is about respect. It is about whether a potential partner and their family see you as a whole person whose life has a logic they are willing to learn, or as a walking salary slip that must fit into their pre-approved box.
You can spend weeks arguing about a startup versus a government job. But the core question is simpler: Are they curious about your world? Have they asked you what a difficult day at your job looks like? Have they asked what part of your work makes you feel proud? This is a negative-space observation you can make: listen for the questions that are never asked. A family that spends an hour interrogating your income but not one minute asking about your work itself is telling you everything you need to know about what they truly value.
The evidence that should allow you to relax, to believe that this is a bridgeable gap, is not when they finally agree that your career is a good one. It is when their questions change. It is when they stop asking, "How much do you make?" and start asking, "How does it work? What do you need to succeed? How can we support you?"
That is the moment you are no longer being measured. You are being seen. And that is a foundation you can build a life on.